Institutional FX Insights: Credit Agricole FX 6/11/26
MACRO & FX STRATEGY BRIEFING: POST-MIDTERM USD EROSION, AI BOOM FRICTION & FISCAL CLIFFS
THE TAKE: THE UNRAVELING OF "TECH EXCEPTIONALISM" PIERCES THE USD SAFE-HAVEN SHIELD
The decisive Democratic capture of Congress creates a multi-front structural headwind for the US Dollar Index (DXY). Beyond short-term volatility, the post-election narrative has ignited concerns that increased regulatory oversight will throttle the AI investment cycle, forcing an institutional reassessment of US technology equity valuations.
Historically, the US current account deficit has relied disproportionately on foreign capital inflows chasing US mega-cap technology and hyperscaler equities. When risk-off episodes are triggered by tech multiple compression and AI capex execution fears, the US Dollar’s traditional safe-haven properties erode at the margin. Foreign investors de-risking US equity allocations unwind dollar hedges and repatriate liquidity, blunting the standard dollar-supportive safe-haven dynamic.
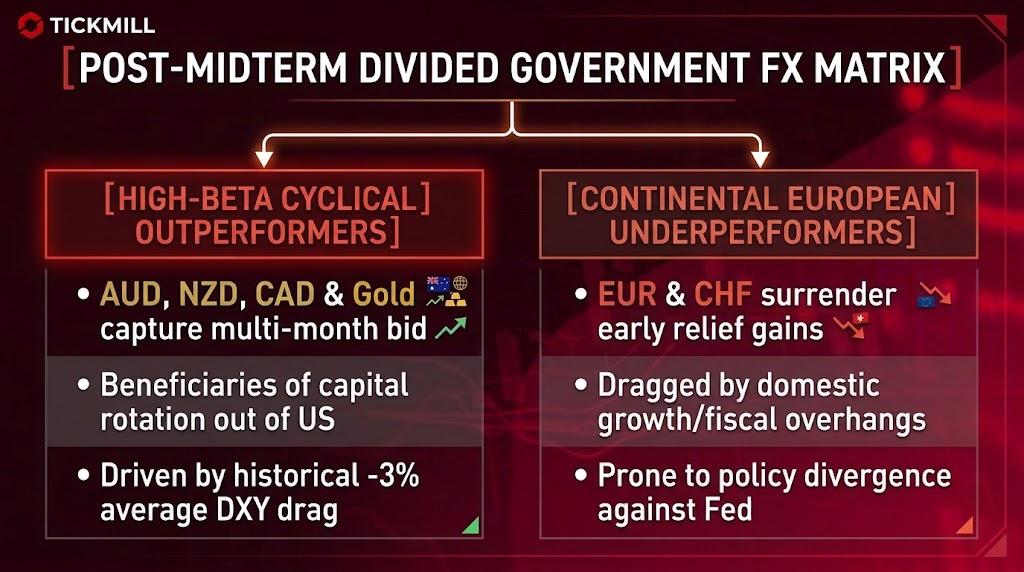
HISTORICAL ANALOG: DIVIDED GOVERNMENT PERFORMANCE (-3% HISTORIC DRAG)
A 50-year historical analysis of currency performance under a Republican President with a Democratic-Controlled Congress reveals clear structural USD underperformance:
Average DXY Trajectory: The US Dollar loses ~3.0% on average over the months following this specific political configuration.
G10 Commodity FX & Gold Outperformance:
Top Performers: The Antipodeans and Cyclicals (AUD, NZD, CAD) alongside Gold historically register the strongest medium-term gains as global capital rotates away from concentrated US assets.
Continental European Laggards: EUR and CHF historically surrender early post-election gains as regional growth differentials and domestic political frictions assert themselves.
LEGISLATIVE GRIDLOCK & THE DECEMBER 11 FISCAL SHUTDOWN CLIFF
Impasse and Presidential Veto Threat: President Donald Trump’s stated willingness to deploy veto authority against Democratic congressional initiatives establishes immediate legislative gridlock, stalling fiscal expansion or targeted tax reliefs.
December 11 Government Funding Deadline: With federal spending authority expiring on December 11, the market faces acute government shutdown tail risk.
Shutdown Safe-Haven Playbook: Historical performance during US federal government shutdown crises demonstrates that Gold and the Swiss Franc (CHF) deliver the most resilient capital protection against localized dollar sell-offs, contrasting with the compromised safe-haven bid of cash USD.
GEOPOLITICAL SKEW VS. TECH SENSITIVITY
Middle East Escalation Risk: Near-term focus remains vigilant toward potential post-election geopolitical re-escalation in the Middle East.
The Dollar Asymmetry: Even if geopolitical hostilities flare up, the US Dollar's safe-haven status remains structurally constrained by its elevated correlation to domestic tech equity liquidations. If military tension drives energy spikes that further pressure tech multiples and equity breadth, the dollar is deprived of its usual flight-to-safety bid.
KEY CATALYST CALENDAR (NEXT WEEK)
US Inflation prints: October CPI and PPI (evaluating whether persistent input costs and wage pressures maintain December Fed hike pricing).
United Kingdom: September Monthly GDP data release.
Central Bank Rhetoric: Heavy slate of G10 central bank speeches (evaluating Fed financial condition tolerances vs. ECB sovereign spread management).
Asia-Pacific Politics: New Zealand General Election, posing localized downside volatility risks for the Kiwi (
NZD).
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!